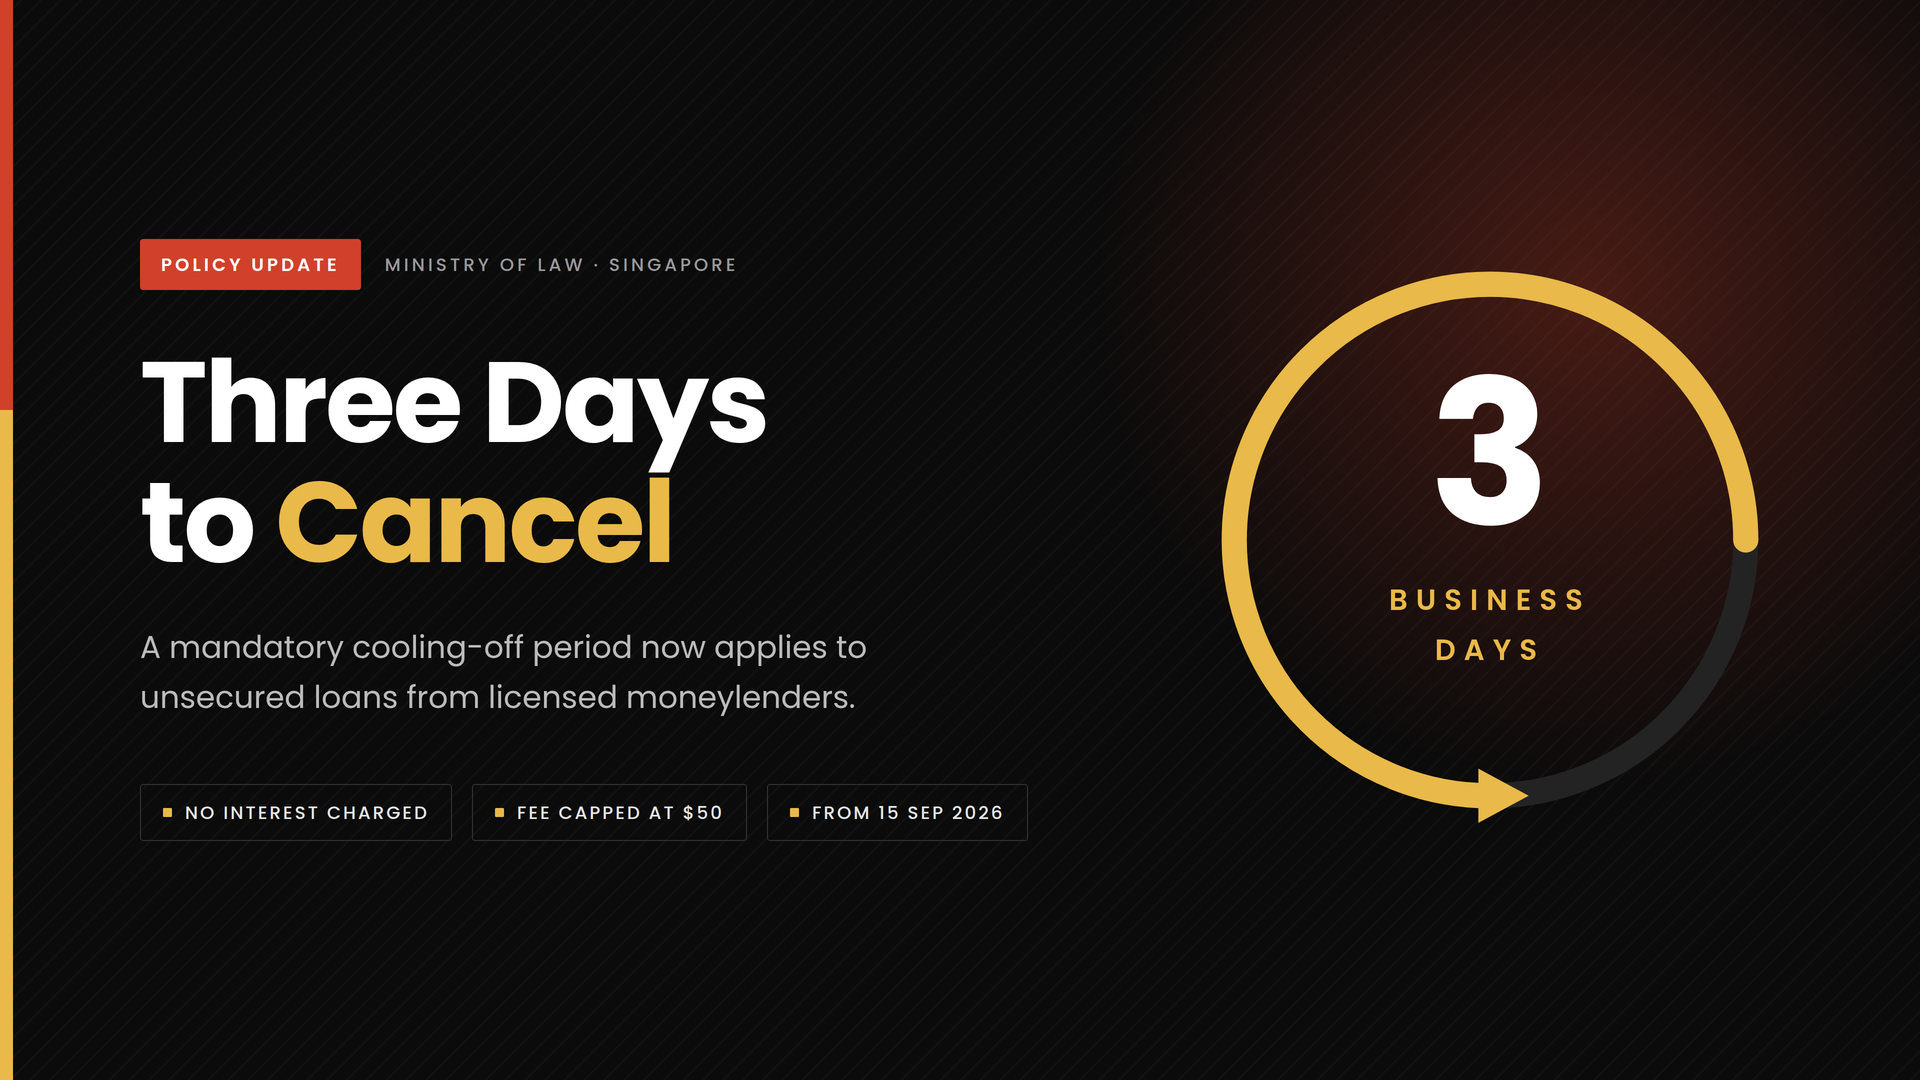
Signing a loan agreement is no longer the point of no return. Since 15 September 2026, anyone who takes an unsecured loan from a licensed moneylender in Singapore has three business days to walk away from it — and the law now caps exactly how much that decision can cost.
The Ministry of Law (MinLaw) announced the mandatory cooling-off period on 31 August 2026. It covers every unsecured loan granted by a licensed moneylender, with one exception: business loans are not included.
The short version: cancel within three business days and you pay no interest at all. The lender may keep only part of the loan approval fee — capped at $50 for loans of $5,000 or less, or 3.5% of the principal for larger loans — and the total you repay can never be more than the loan principal itself.
How the three-day window is counted
The clock runs on business days only. Saturdays, Sundays and Singapore public holidays do not count toward the three days, so a loan taken just before a long weekend gives you the same amount of real decision-making time as one taken midweek.
Within that window you may cancel the loan outright. Before this rule existed, cancelling was possible but expensive: the moneylender was entitled to keep the entire loan approval fee, plus any interest that had already accrued. That is what has changed.
What it costs to cancel
Two things happen when you cancel inside the cooling-off period. First, no interest is charged — not a reduced rate, but none. Second, the moneylender may retain only a limited slice of the approval fee, to cover the paperwork and due diligence already done on your application.
| Principal of the unsecured loan (non-business) | Maximum the lender may retain |
|---|---|
| $5,000 or less | $50 — and never more than the approval fee actually charged |
| More than $5,000 | 3.5% of the principal — and never more than the approval fee actually charged |
In every case, the total amount you repay cannot exceed the principal of the loan.
So the sum you return is simply the money that actually reached your hands, plus the capped portion of the approval fee. Nothing else.
| A worked example: a $1,000 loan, cancelled in time | |
| Loan principal | $1,000 |
| Approval fee deducted upfront (10%, the legal maximum) | −$100 |
| Cash you actually received | $900 |
| Fee the lender may keep on cancellation | $50 |
| Interest charged | $0 |
| Total repayable on cancellation | $950 |
Why the rule was introduced
MinLaw developed the framework together with the Credit Association of Singapore, the professional body representing licensed moneylenders. The intent is a balance: borrowing decisions are sometimes made under pressure or on impulse, and a short window lets someone reconsider whether they really need the credit — while lenders are still compensated for work genuinely carried out in granting the loan.
The 15 September start date was set deliberately, giving licensed moneylenders time to adjust their internal processes and systems. The Registry of Moneylenders, which sits under MinLaw, continues to work with the industry on implementation.
Other borrower-friendly practices being encouraged
The cooling-off period is not the only change. In April 2026, the Registry updated its Professional Service Handbook for licensed moneylenders, encouraging the industry to adopt three practices:
- Rewarding good repayment behaviour — discounts or rebates on interest or fees for borrowers who pay on time or settle ahead of schedule.
- Building digital touchpoints, such as an online portal where borrowers can track their own loan servicing.
- Reaching out to borrowers in difficulty before the situation worsens — restructuring repayments to something workable, or referring them to a Social Service Agency.
These protections only apply to licensed lenders
Every safeguard described here exists because licensed moneylenders operate under the Moneylenders Act. Unlicensed lenders are bound by none of it.
Two quick checks are worth remembering. A licensed moneylender cannot solicit you through text messages, phone calls, or social media — an unsolicited loan offer in your inbox is a red flag on its own. And before granting a loan, a licensed moneylender must meet you in person at its approved place of business to verify your identity face to face. The full list of licensed moneylenders is published on MinLaw’s Registry of Moneylenders.
If you are weighing up a loan, the new rule gives you something you did not have before: a few days of breathing room, at a known and limited cost.
Source: Ministry of Law, Singapore — Mandatory Cooling-off Period for Loans Taken from Licensed Moneylenders, 31 August 2026.